Table of Content
The ESIC new rules 2026 bring important changes to how employers determine employee eligibility and calculate ESI contributions under the Code on Social Security, 2020. The ESI salary limit remains ₹21,000 per month, while the revised definition of wages under the new Labour Code affects how employers assess coverage and calculate contributions.
Employees covered under the ESI scheme generally contribute 0.75% of applicable wages, while employers contribute 3.25%. These contribution rates remain unchanged, but HR and payroll teams must review salary components carefully to apply the revised wage definition correctly.
This guide explains the ESIC salary limit in 2026, ESI calculation under the new Labour Code, employee eligibility, contribution rates and important compliance requirements that employers should understand.
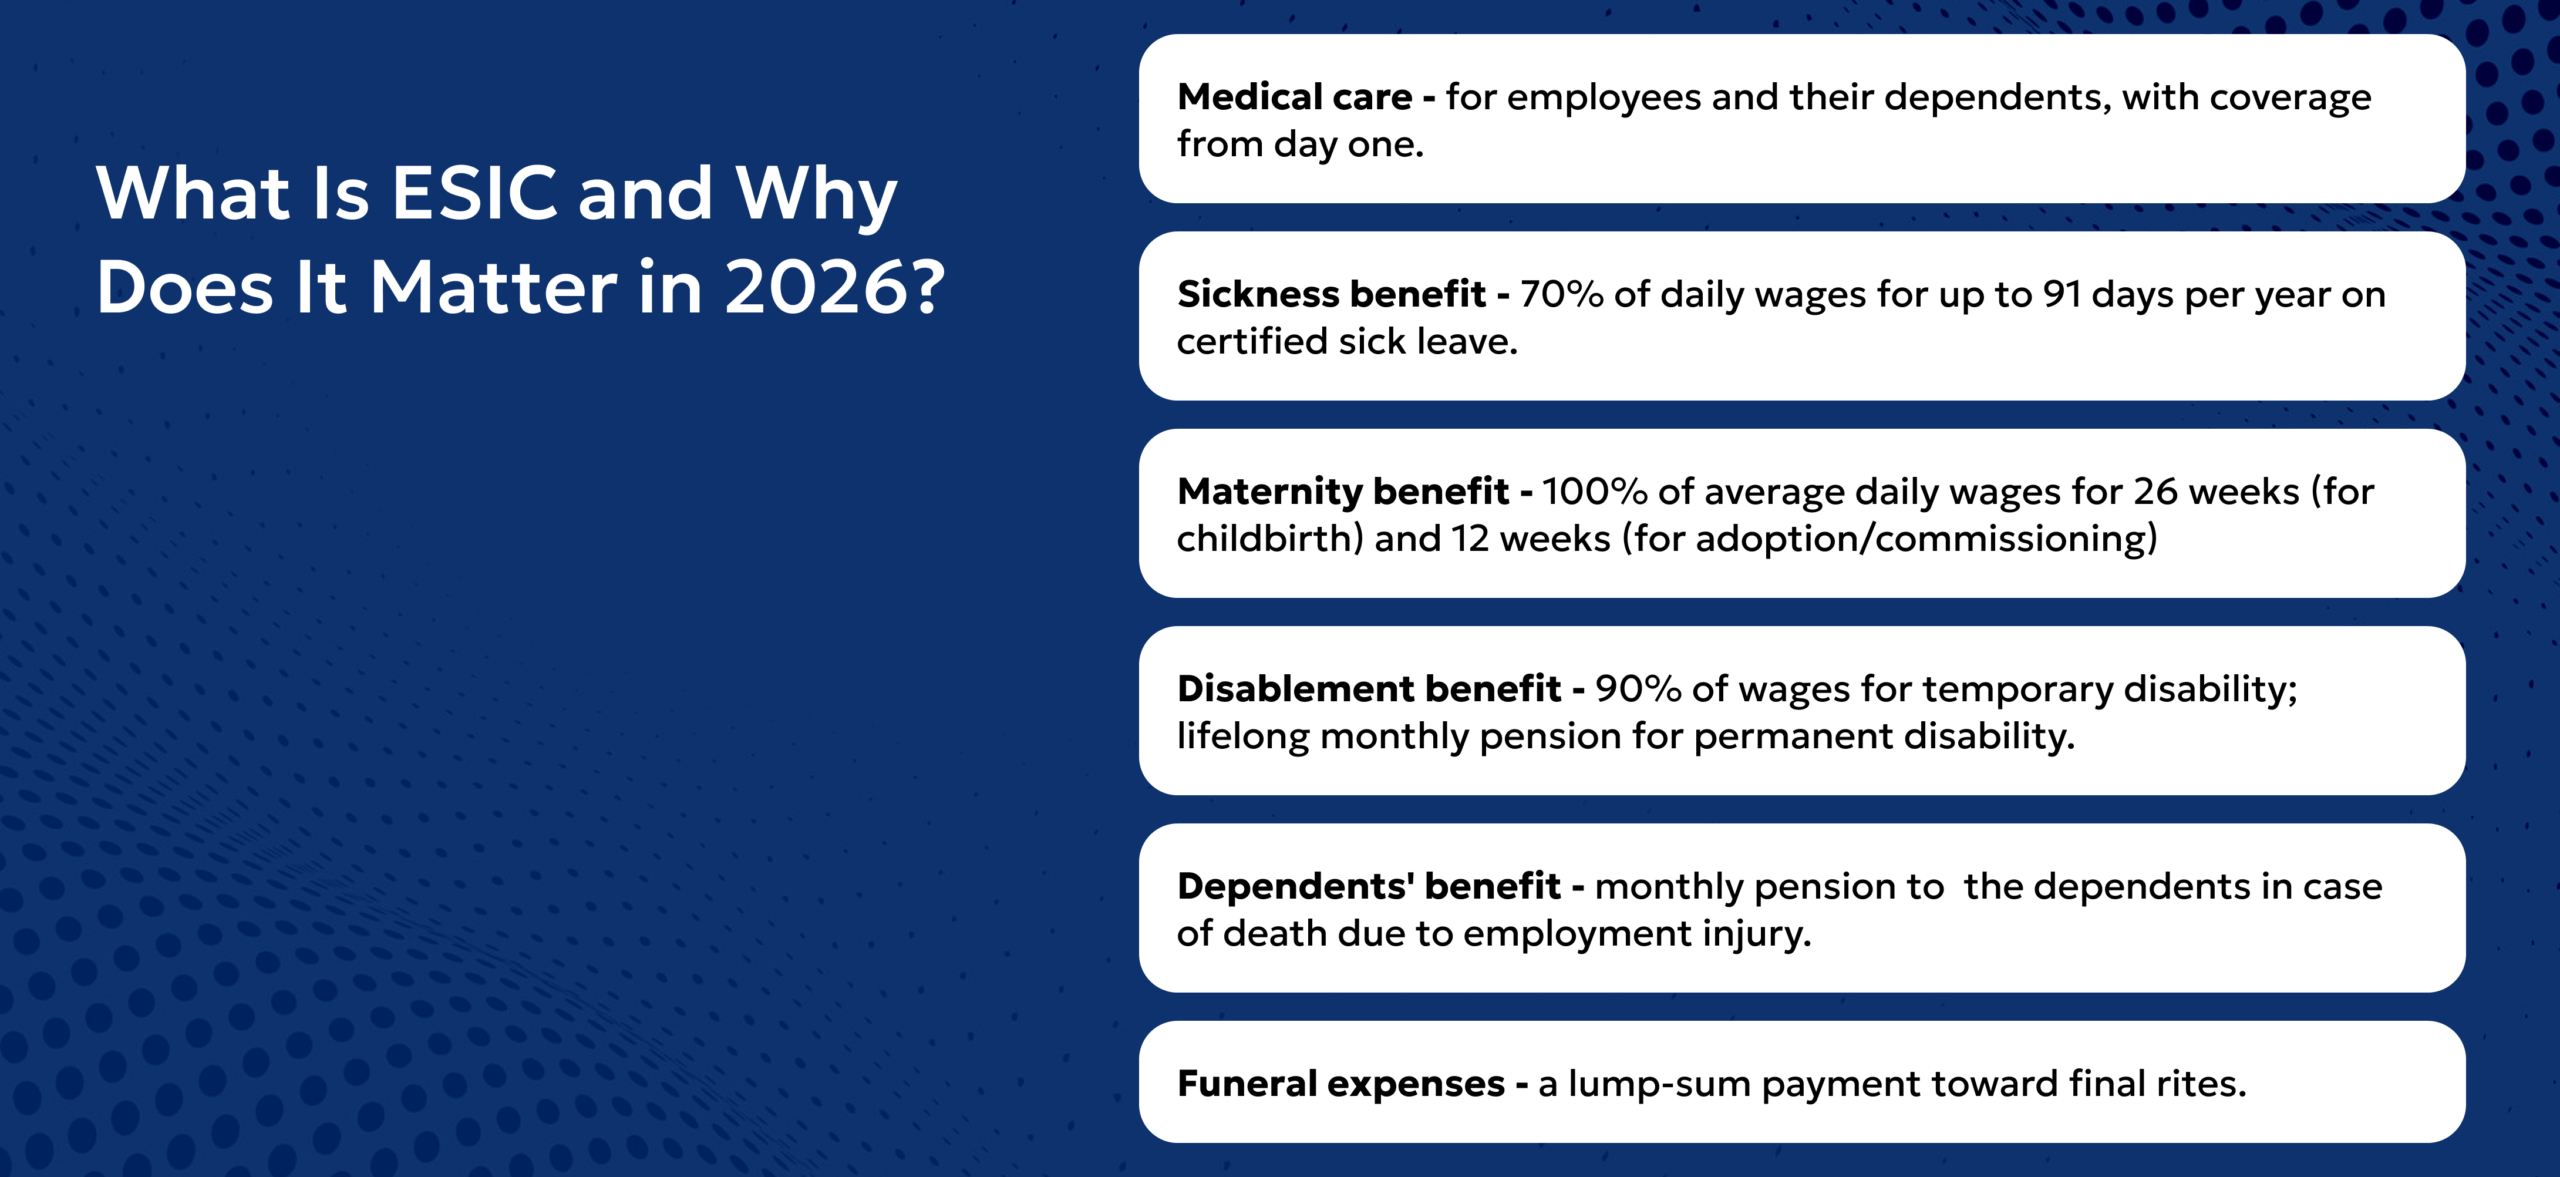
The Employees’ State Insurance Corporation (ESIC) operates under the Ministry of Labour and Employment, Government of India, and administers one of the world’s largest integrated social security schemes for workers. Governed by the ESI Act, 1948, the scheme provides employees with a comprehensive safety net covering:
Not sure whether your current payroll and ESIC processes meet the latest compliance requirements? Let our experts review them.
This is the single most impactful change driving all new ESIC rules in 2026.
Under the old ESI Act framework, ESIC applicability was calculated on gross salary, which included all allowances. Employers could (and often did) structure salary with a low basic pay and high allowances, keeping the ESIC-taxable component artificially low.
Under the Code on Social Security, 2020 (Section 2(88)), the definition of “wages” has been redefined. The key provision:
Why This Matters for HR Teams:
| Old Rule | New ESIC Rule 2026 |
|---|---|
| ESIC on gross salary (all allowances included) | ESIC on revised wages: Basic + DA, minimum 50% of CTC |
| Low Basic + High Allowances = lower ESI liability | Basic cannot be kept artificially low |
| Fewer employees under ESIC cover | Significantly more employees now under coverage |
| Salary restructuring for ESI avoidance was common | Salary restructuring must now comply with the 50% rule |
Practical Example:
Since allowances (₹22,000) exceed 50% of total wages, the excess (₹22,000 – ₹15,000 = ₹7,000) is added back to basic. Revised wages = ₹8,000 + ₹7,000 = ₹15,000.
Since ₹15,000 < ₹21,000, this employee now falls under ESIC coverage, even though their CTC is ₹30,000.
The ESIC salary limit in 2026 is ₹21,000 per month for general employee coverage. The Ministry of Labour and Employment has confirmed that the existing notified wage ceiling continues to apply under the Code on Social Security, 2020.
However, ESIC eligibility is determined using the applicable statutory definition of wages, not automatically by an employee’s total CTC or gross salary.
Under the revised definition, wages generally include basic pay, dearness allowance and retaining allowance, where applicable. If excluded allowances exceed the permitted 50% threshold, the excess is added back to wages.
For employees with disabilities, the higher notified wage ceiling of ₹25,000 per month continues to apply, subject to the relevant provisions.
Employers should review employee salary structures and coverage conditions carefully before deciding whether ESI applies. For businesses looking to understand the registration requirements, our guide on ESIC registration, eligibility and documents required explains the employer registration process.
Official Reference: The Ministry of Labour and Employment provides clarification on the current wage ceiling and applicability under the Labour Codes in its October 2026 Labour Codes FAQ PDF.
Under the Code on Social Security, 2020:
Under the old ESI Act, ESIC coverage was restricted to notified areas and specific establishment types. The Code on Social Security eliminates this geographic restriction, extending ESIC coverage to all establishments with 10 or more employees across all districts in India.
This means businesses operating in smaller towns, tier-2 cities, or areas previously outside ESIC’s notified zones may now be covered for the first time.
ESIC launched its Scheme for Promotion of Registration of Employers and Employees (SPREE 2025), a one-time amnesty allowing unregistered employers to register without paying past dues, interest, or penalties.
The deadline, extended to January 31, 2026, has now passed.
Employers who did not register under SPREE are now subject to:
Avoid ESIC registration gaps, contribution errors and missed compliance requirements with expert assistance.
| Contributor | Rate | Basis |
|---|---|---|
| Employer | 3.25% | Of applicable ESI contribution wages |
| Employee | 0.75% | Deducted from the employee’s salary |
| Total ESI Contribution | 4.00% | Per covered employee per month |
Key rules:
Half-Yearly Return Filing Deadlines:
| Contribution Period | Return Due Date |
|---|---|
| April – September | 11 November |
| October – March | 11 May |
Make ESIC compliance easier for your HR and payroll teams with reliable end-to-end support.
ESI is calculated on gross wages, not basic salary, not CTC, and not net take-home. This includes basic salary, DA, HRA, conveyance allowance, overtime, and all regular cash payments.
The most expensive error in ESIC compliance is using basic salary (the way PF is calculated) for ESI as well. The result is a systematic monthly shortfall, visible in every inspection.
When an employee’s salary crosses ₹21,000 mid-period, ESI coverage does not stop immediately. The ESI scheme operates in two contribution periods (April–September and October–March). An employee who crosses the wage ceiling during a period stay covered until the end of that period.
Stopping deductions mid-period creates a contribution gap that ESIC’s system flags automatically during half-yearly return reconciliation.
If your payroll structure keeps Basic below 50% of total CTC, it is non-compliant with the Code on Social Security, 2020. HR and payroll teams must audit every employee’s salary structure and re-issue appointment letters where the structure has changed.
Late deposits attract 12% per annum of interest from day one. Processing payroll on the 28th and depositing ESIC on the 30th is a formula for accumulating interest liability month after month.
Best practice: target the 12th–13th of each month as your internal ESIC payment deadline.
Based on 25+ years of statutory compliance experience, here is what HR and payroll teams must implement to stay ahead of the new ESIC rules 2026:
Pull a full payroll report and check each employee’s Basic + DA as a percentage of gross CTC. Flag all cases where Basic + DA is below 50% of total wages. These employees may be newly covered under the revised wage definition, even if their CTC appears above ₹21,000.
Set up an internal alert in your payroll software for employees approaching the ₹21,000 gross wages threshold. When an increment pushes someone above it, note the contribution period and continue coverage until the period ends, then exit them from the next period.
Most legacy payroll systems calculate ESI on gross salary without applying the 50% rule. This needs to be updated. Ensure your HRMS or payroll tool can:
| Task | Deadline |
|---|---|
| Monthly ESIC contribution deposit | 15th of every month |
| New employee ESIC registration | Within 10 days of joining |
| Establishment ESIC registration (if newly applicable) | Within 15 days of trigger |
| Half-yearly return (Apr–Sep period) | 11 November |
| Half-yearly return (Oct–Mar period) | 11 May |
Given the complexity of the new ESIC rules 2026, the expanding scope of the Code on Social Security, and the increasingly digital nature of ESIC enforcement, many HR teams in Bangalore and across India are choosing to outsource their ESIC compliance to specialists. This reduces the risk of errors, ensures timely filings, and keeps you audit-ready at all times.
Need help reviewing employee eligibility, ESIC contributions or contractor compliance? Our team can assist.
Understanding the cost of getting it wrong is important for every HR and payroll team:
| Violation | Penalty |
|---|---|
| Late ESIC contribution deposit | 12% per annum of interest from the 16th |
| Extended delay (beyond 2 months) | Damages: 5% to 25% of arrear amount |
| Failure to register employees | Fine up to ₹10,000 + up to 3 years imprisonment |
| Repeated/willful non-compliance | Fines up to ₹3,00,000 + imprisonment |
| Non-coverage of contract workers | Back-contribution + damages + prosecution |
| Not maintaining statutory registers | Subject to ESIC inspection and penalty |
At Vishaal Consultancy Services, we have been navigating India’s statutory compliance landscape for 25+ years, working with 250+ businesses across Bengaluru, Delhi, Mumbai, Kolkata, and across India.
Our ESIC compliance services include:
The ESIC new rules 2026 represent the most significant structural shift in India’s social security framework in over a decade. The combination of the new wage definition under the Code on Social Security, expanded coverage to gig workers, and nationwide applicability means that more employers and more employees are covered under ESIC than ever before.
For HR and payroll teams, the message is clear: audit your salary structures, update your payroll systems, review your contractor compliance, and plug every gap before an inspection does it for you.
The post-SPREE enforcement environment in 2026 is not forgiving. The good news is that with the right systems, the right processes, and the right compliance partner, staying ESIC compliant is not complex; it just requires consistency and expertise.
Do not wait for an ESIC inspection to tell you what is wrong. Get in touch with Vishaal Consultancy Services today and let us handle your ESIC compliance accurately, on time, every time.
Keep your ESIC processes accurate, timely, and ready for compliance reviews.
No. The contribution rates remain 3.25% (employer) and 0.75% (employee), unchanged since July 2019. Together, the total is 4% of gross wages per covered employee.
The current ESI wage ceiling is ₹21,000 per month in gross wages (₹25,000 for persons with disabilities). As of April 2026, no official notification has increased this limit, though a revision to ₹25,000–₹30,000 is under review.
Under Section 2(88) of the Code on Social Security, 2020, Basic + DA must constitute at least 50% of total wages. If allowances exceed 50%, the excess is added back to wages for ESI calculation – potentially bringing more employees under coverage than before.
Yes, in principle. The Code on Social Security, 2020, includes gig and platform workers within the social security framework. Coverage obligations will apply as states notify rules under the Code. If your business uses platform-based or app-based workers, monitor state-level notifications closely.
The employer may face a fine of up to ₹10,000 and contribution liability from the date of employment. In serious cases, prosecution under the ESI Act with imprisonment up to 3 years is possible.
Yes. Contract workers deployed at your premises – through a staffing agency or otherwise – count toward the 10-employee threshold. If they earn below ₹21,000 in gross wages, you must ensure ESIC coverage for them. If the contractor defaults, the principal employer carries secondary liability.
The return for April–September is due by 11 November. The return for October–March is due by 11 May.
See Related Blogs
BLOGS
BLOGS
BLOGS
Fill in your details to download our New Labour Code PDF.
Fill in your details to download our exclusive e-learning document.
Fill in your details to download our exclusive e-learning document.
Fill in your details to download our exclusive e-learning document.